What If We Looked at Our Resources Differently?

Before we ask how to produce more, perhaps we should ask whether we have understood the full value of what we already have.

For generations, we have built industries around a relatively simple question:

“What can we make from this resource?”

We grow a crop for a particular product. We harvest seaweed for a particular application. We process food to recover the component we want. We treat wastewater primarily to make it safe for disposal or reuse.

And once those systems have been established, we tend to keep improving them, by making them faster, bigger, more efficient. And usually, more costly…

But perhaps there is a more fundamental question we should be asking first:

“What value does this resource actually contain?”

Not what have we traditionally used it for.

Not what our existing processing infrastructure was designed to produce.

Not even what today’s market currently values most highly.

But what is in it? What could be recovered from it? And what could it become?

Only then should we ask: How should we process it? That reversal in thinking may seem subtle, but it has profound implications.

Designing the process around the resource

Too often, we approach biological resources with the processing method already decided.

The resource is made to fit the process.  What if we reversed that?

Imagine beginning with the biological resource itself and mapping its potential value: proteins, fibres, minerals, oils, pigments, nutrients, bioactive compounds, carbohydrates and other potentially useful fractions.

Then, instead of asking which of these survives our existing process, we ask:

“What processing approach would allow us to preserve and recover the fullest possible value?”

The process is designed around the resource.  Not the resource around the process.

This is the thinking behind Value Unlocking and Value Recovery.

Value Unlocking is about recognising potential that may previously have been overlooked.

Value Recovery is about designing systems capable of retaining and recovering more of that value.

Together, they ask us to look at familiar resources through an unfamiliar lens.
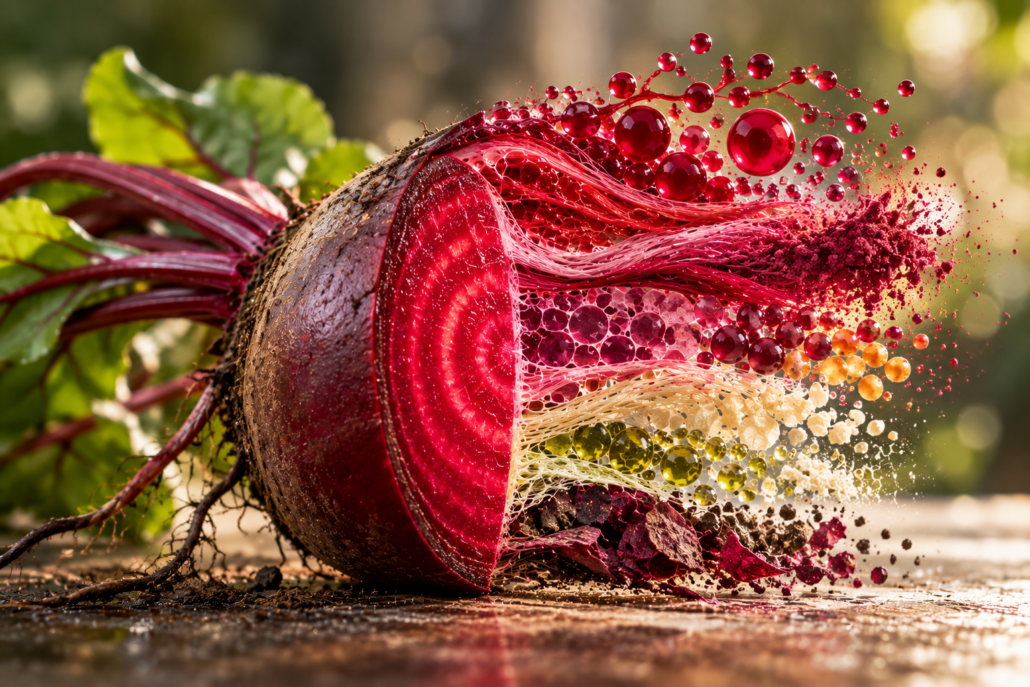
The same resource. A different question.

This matters because many of the resources we describe as constrained, low-value or waste may not necessarily be so.

They may simply be under-understood and under-utilised. For example:

A tonne of seaweed remains a tonne of seaweed.

A beetroot remains a beetroot.

A citrus fruit remains a citrus fruit.

Agricultural residues, spent grain and organic effluent remain physically what they were yesterday.

But their economic potential can change dramatically when we stop asking: “What do we normally do with this?”

and begin asking: “What else is here?”

That is a very different starting point for innovation.

Before producing more, recover more

This shift also challenges one of the assumptions underpinning modern industrial growth.

When demand increases, our instinct is usually to produce more.

More hectares.

More biomass.

More yield.

More extraction.

More throughput.

Sometimes that will be necessary.  But on a planet facing increasing pressure on land, water, energy and natural systems, there is another option we should investigate first: Can we derive more value from the resources we are already producing?

If we can recover more useful outputs from the same biological input, productivity begins to mean something different.  It is no longer simply yield per hectare or tonnes per hour.

It becomes: value recovered per unit of resource.

That could be one of the more important measures of productivity in the emerging bioeconomy.

Waste looks different through this lens

It also changes how we think about so-called ‘waste’.

Waste is generally treated as something that exists at the end of a process.

We then invest enormous effort trying to recycle it, repurpose it, dispose of it more responsibly or find another market for it.

Those efforts remain important.  But Value Recovery asks an earlier question:

“Why did so much value become waste in the first place?”

If useful compounds are destroyed, diluted, discarded or rendered uneconomic during processing, the opportunity to recover them may already have been lost.

So perhaps the most effective place to address waste is not always at the waste stream.

Perhaps it is at the beginning of the process.

A different lens

None of this requires us to abandon the infrastructure, industries or knowledge we already have. It does, however, ask us to interrogate them.

Science has given us an extraordinary understanding of the complexity contained within natural resources.  Technology increasingly gives us new ways of accessing that complexity.

The opportunity now is to bring those two things together.

At Green Cell Technologies, we believe this requires a shift from simply processing biological resources towards understanding, unlocking and recovering their value.

Our own technology is one expression of that thinking.

But the principle is much bigger than any single technology or company.

It is a question that can be asked of a crop, a forest, seaweed, a food manufacturing stream, wastewater or almost any biological resource: “What value is already here that we are failing to see?”

Because sometimes innovation does not require a new resource.  Sometimes it begins by looking differently at the one already in front of us.

Same resource. Different lens. Greater value.

Roy Henderson is CEO of Green Cell Technologies® (GCT®), a biotechnology company developing and licensing processing technology built around Value Unlocking and Value Recovery – identifying and recovering greater value from existing biological resources.

Get in touch to discover, unlock and recover the best value in your existing resources and systems by emailing info@greencelltechnologies.com
Food Security in an Age of Compounding Shocks

War, climate and disrupted supply chains are exposing the fragility of how we grow food. Perhaps resilience begins by making better use of the biological resources already available to us.

“Food security cannot depend indefinitely on everything going right at the same time. We need agricultural systems capable of functioning when things go wrong.” – Roy Henderson, CEO, Green Cell Technologies®

The modern food system is an extraordinary feat of global co-ordination.

Energy is produced in one part of the world. Fertiliser in another. Crops somewhere else. Ships move between them. Farmers plant according to relatively predictable seasons, and global supply chains keep the inputs moving.

Until they don’t.

In 2026, several pressures that would normally be considered individually are occurring simultaneously.

Conflict is disrupting energy and fertiliser production. Critical shipping routes are under pressure.  Fertiliser prices have risen sharply. El Niño presents additional risks to agricultural production. And farmers must somehow absorb all of this while continuing to produce affordable food.

The question is no longer whether any single shock can be managed.

It is how many shocks the global food system can absorb at the same time.

Fertiliser has become a geopolitical vulnerability.

The scale of the world’s dependence on a small number of trade routes is striking.

According to the International Energy Agency, more than 30% of globally traded urea passes through the Strait of Hormuz, together with approximately 20% of traded ammonia and phosphate and around half of global seaborne sulphur – all important to fertiliser supply chains.

The Food and Agriculture Organization (FAO) recently reported that tanker movements through the Strait had fallen by more than 90%, with an estimated 1.5–3 million tonnes of fertiliser trade being delayed each month.

FAO Director-General Qu Dongyu has warned that fertiliser scarcity resulting from the disruption could translate into “lower yields and tightening food supplies” through the latter part of 2026 and into 2027.

The economics are already changing.

The World Bank forecasts fertiliser prices to increase by approximately 31% in 2026, driven partly by a 60% increase in urea prices. The International Energy Agency reports that urea prices doubled between January and May.

For farmers, particularly in import-dependent economies, fertiliser is therefore becoming not merely an agricultural input.

It is becoming a geopolitical risk.

And then there is climate

Layer climate volatility over these disruptions and the vulnerability becomes more apparent.

The World Bank has identified the potential combination of El Niño, elevated energy and fertiliser costs, biofuel demand and trade restrictions as significant risks to global food markets during 2026.

This does not mean the world is inevitably heading towards a global famine. On paper, global cereal stocks remain relatively comfortable by historical standards.

But global availability is not the same as food security.

Food has to be affordable, accessible – and able to move from where it is produced to where it is needed.

That distinction is particularly important for Africa and the Middle East. 

Russia and Ukraine together account for around one-third of global wheat trade, much of it traditionally moving through Black Sea ports. Ukraine alone has historically been a major source of affordable grain for countries across Africa, the Middle East and Asia.

So grain sitting in a silo in Ukraine or Russia does little for a food-importing country if Black Sea routes are constrained, shipping costs soar, fertiliser prices rise and another critical route through the Red Sea or Strait of Hormuz is simultaneously disrupted.

The World Food Programme now describes these simultaneous pressures across the Black Sea, Red Sea and Strait of Hormuz as a potential “triple chokepoint” for global food security.

The danger, therefore, is not simply that the world runs out of grain.

It is that food and the inputs required to produce it become increasingly expensive, inaccessible or stranded in the wrong place – while the populations most dependent upon imports are least able to absorb the shock.

That should make us think differently about resilience.

If fertiliser becomes significantly more expensive or difficult to obtain at precisely the moment crops are experiencing greater heat, drought, salinity or other environmental stresses, simply trying to maintain the existing agricultural model becomes increasingly difficult.

Perhaps the question shouldn’t only be: Where will we get enough fertiliser?

It should also be: How can we help plants make better use of the resources available to them?

Looking to the sea

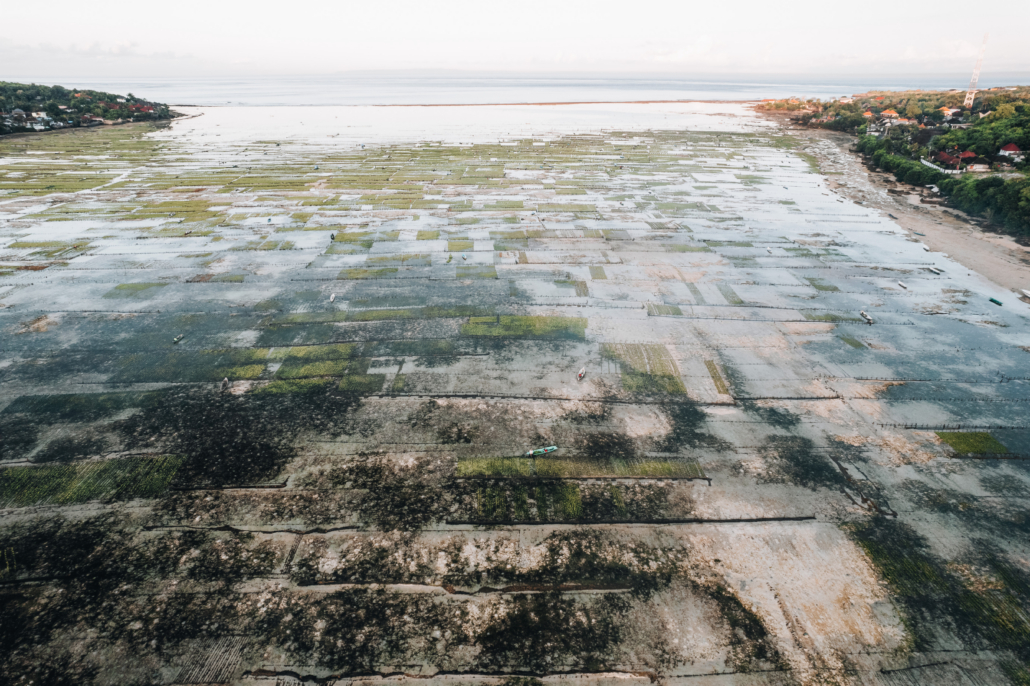
Aerial Drone Photo of Seaweed Farms in Nusa Lembongan Ceningan Bali Indonesia. High quality photo

This is where seaweed becomes interesting.

Seaweed-derived agricultural bio-stimulants are attracting increasing scientific attention because of their ability to influence plant growth, nutrient-use efficiency and responses to environmental stress.

They are not replacements for nitrogen, phosphorus and potassium.

NPK fertilisers provide essential plant nutrients.  Bio-stimulants work differently.

Research published in the Journal of Biotechnology describes seaweed-derived bio-stimulants as containing diverse bioactive compounds – including polysaccharides, proteins, polyphenols and vitamins – associated with improved plant growth, stress tolerance and soil health.

Other research points to seaweed polysaccharides that can support water retention, nutrient uptake and plant performance under conditions including drought, salinity and extreme temperatures.

In other words, fertiliser feeds the plant.

Bio-stimulants can potentially help the plant use what it has more effectively and cope better when conditions become difficult.

In a world of increasingly expensive inputs and climatic stress, that distinction matters.

From Sargassum problem to biological resource

Then consider Sargassum.

Enormous seasonal influxes of the seaweed have created environmental and economic problems across parts of the Caribbean and Atlantic. The conventional starting point is understandable:

How do we get rid of it?

But what happens if we ask a different question?

What value does it contain?

Recent research has already investigated Sargassum-derived agricultural products. A 2026 study of a Sargassum-based liquid bio-fertiliser used on tomatoes found increased availability of several soil macronutrients during the study.

Importantly, the research also illustrates why processing matters.

Raw Sargassum can contain high levels of salt and potentially concerning trace elements, including arsenic.  It cannot simply be collected from a beach and spread indiscriminately across agricultural land.

The resource must be understood, undesirable components must be identified, and the valuable components must be recovered safely and effectively.

The processing method must be designed around the chemistry of the resource.

That is Value Recovery in practice.

GCT’s role: recover more from what already exists

At Green Cell Technologies, we see two opportunities emerging from this changing food-security landscape.

The first is agricultural resilience – using technologies such as the Disruptor® to process seaweed and other biological resources differently may enable greater recovery and availability of useful compounds for bio-stimulant applications.

That could include cultivated seaweeds, existing marine biomass and, where appropriate and properly characterised, problematic biomass such as Sargassum.

The objective is not to claim that seaweed can replace conventional fertiliser. It is more interesting than that:  Can biological inputs help farmers make every kilogram of fertiliser, every litre of water and every hectare of productive land work harder?

The second opportunity is on the other side of the farm gate – it is meaningful nutrition.

Food security should not be measured solely in tonnes or calories.  Our crops, food-processing streams and agricultural by-products contain proteins, fibres, micronutrients and functional compounds that conventional processing does not always fully recover.

Value Recovery asks how we can retain and recover more of that nutrition from resources already being produced.

Put simply:

Help the plant derive more from its environment.

Then help humanity derive more from the plant.

Resilience through value

None of this means that conventional fertiliser is unnecessary.

Nor does it mean that a single technology can insulate agriculture from war or climate change.

The challenge is larger than that.

Indeed, in August, the World Bank and other multilateral development institutions called not only for stronger fertiliser supply chains but also for improved fertiliser-use efficiency, diversified nutrient sources, healthier soils and more resilient food systems.

That is the direction in which we need to move.

The current crisis should not be welcomed.  Fertiliser scarcity threatens farmers, yields and ultimately food affordability.

But it does expose something we can no longer ignore.

A food system dependent upon concentrated sources of energy, fertiliser, favourable weather and uninterrupted global shipping is vulnerable when several of those assumptions fail simultaneously.

Resilience will require diversification.  It will require better soil management, smarter use of fertiliser and new biological inputs.  And it will require us to look much more carefully at resources we already have – on farms, in oceans and within existing food-production systems – and ask:

What value is already here that we haven’t yet learned to recover?

Because the answer to food insecurity cannot always be to produce more.  Sometimes resilience begins with getting considerably more from what we already have.

Roy Henderson is CEO of Green Cell Technologies® (GCT®), a biotechnology company developing and licensing processing technologies centred on Value Unlocking and Value Recovery.

Why Most Beetroot Powders Never Deliver Their Promised Performance

And why manufacturing economics are as important as nutrition 

Beetroot doesn’t have an awareness problem.

Its naturally occurring nitrates and their relationship with nitric oxide have been extensively studied, particularly in relation to exercise performance and vascular health.

As a result, beetroot has become a familiar ingredient across sports nutrition, functional foods, powders, supplements and beverages.

But there is a question the industry asks far less frequently:

How much of the value originally contained in that beetroot survives processing and makes it into the final ingredient?

That may prove to be a much more important question than we think.

At Green Cell Technologies® (GCT®), we have long argued that the biological material itself is only part of the ingredient story.

Same plant. Different outcome.

Plants are extraordinarily sophisticated chemical structures containing proteins, fibres, minerals, pigments and thousands of other naturally occurring compounds.

The challenge is accessing them.

Conventional food processing frequently separates, presses, peels, heats, mills or otherwise processes plant material to create ingredients that manufacturers can conveniently formulate into consumer products.

But every processing decision potentially determines what is retained, what remains inaccessible and what is discarded.

Beetroot provides an unusually clear demonstration of this.

Recently, GCT processed 2,000kg of beetroot through RWH’s (DCD® license holders) Cape Town pilot facility using our patented Dynamic Cellular Disruption® (DCD®) process. The resulting powder and a selection of commercially purchased beetroot powders were subsequently submitted for comparative testing at accredited commercial laboratories, including SGS. 

The results raise an important question for ingredient manufacturers:

Are we measuring the potential of the crop – or the consequences of the processing method?

What the laboratory found:

Compared with the conventionally processed consumer beetroot powders tested, DCD® processed beetroot recorded:

  • 410.95% higher natural nitrate content
  • 2,570% more dietary fibre
  • 226.5% more protein
  • 283.94% more natural calcium
  • 199.25% more natural potassium
  • 146.31% more natural magnesium
  • 7,600% more natural iron
  • 21.07% more Vitamin C

Available carbohydrates were also 49.7% lower in the DCD® product tested. 

These are not different varieties of beetroot engineered to produce different outcomes.

The fundamental difference is processing.

And that distinction matters.

Processing is part of ingredient performance

Conventionally, beetroot powder is commonly produced in one of two ways.

Beetroot may be pressed into juice and subsequently spray-dried, often using a carrier, creating a residual pomace stream. Alternatively, the beetroot may be air- or freeze-dried and milled.

GCT takes a different approach.

Dynamic Cellular Disruption® is a non-thermal, non-chemical process designed to open more than 99% of cellular structures. In beetroot production, the whole vegetable can be washed, minced, passed through the Disruptor®, dried and subsequently milled into powder. 

That means material traditionally removed or discarded can instead remain part of the finished ingredient.

And therein lies a much bigger industrial opportunity.

From waste reduction to Value Recovery

Sustainability discussions in food manufacturing have historically focused heavily on waste.

How do we dispose of less?

How do we divert by-products from landfill?

How do we find secondary applications for processing residues?

These are important questions.

But perhaps we should ask an earlier one:

Why create the waste stream in the first place?

The beetroot used in GCT’s trial was not premium retail produce. It included so-called “ugly produce” that could otherwise have been rejected because of cosmetic considerations. Yet the biological compounds contained within the cells do not disappear because the vegetable fails a supermarket beauty test. 

This is where GCT’s concept of Value Recovery becomes important.

Value Recovery is not simply about turning waste into something useful after it has been created.

It is about designing processing systems that recover more of the nutritional, functional and commercial value – before that value is lost.

The question changes from: “What can we do with our waste?”

to: “Why are we allowing valuable material to become waste?”

The economics may be as important as the nutrition

There is another consequence.

If more of the desired compounds can be recovered from the same amount of biological material, manufacturers may require less of an ingredient to achieve a targeted formulation.

In GCT’s comparative beetroot analysis, the conventional powder was calculated at an average dosage of approximately 22.5g. Based on the nitrate concentrations measured, approximately 4–5g of DCD® Beetroot Powder could provide an equivalent nitrate quantity.

GCT’s indicative calculation puts ingredient cost at approximately $0.37 per serving for the conventional powder compared with approximately $0.07 for the DCD® product – an estimated reduction of around 81% per serving. 

That changes the discussion from sustainability alone to manufacturing economics.

A smaller functional dose potentially affects formulation space, packaging, logistics, ingredient costs and the commercial possibilities for the finished product.

Beetroot is the case study. Processing is the story.

The significance of these findings therefore extends well beyond beetroot.

Agriculture has spent decades trying to produce more. More tonnes per hectare, more biomass, more yield and so on. But biological resources already contain enormous value.

The industrial biotechnology opportunity is increasingly about recovering more of it, and at GCT, we believe the next significant productivity gain in biological manufacturing may not come from growing more raw material.

It may come from extracting more value from every tonne we already grow.

That is the science of Value Recovery.

Put your own raw material to the test

GCT develops, sells and licenses its patented Disruptor® technology to manufacturers globally.

Rather than asking manufacturers to accept the principle in theory, we prefer to demonstrate it on their own material.

If you manufacture or process fruit, vegetables, botanicals, seaweed, algae, grains, seeds or other biological materials, get in touch to discuss a trial.

GCT can evaluate how the material responds to Dynamic Cellular Disruption® and help identify opportunities for improved extraction, greater whole-material utilisation, waste reduction and Value Recovery.

Your current waste stream may contain considerably more value than you think.

Email us today on: info@greencelltechnologies.com

Value Recovery: Unlocking More Value from Biomass

Recovering value is becoming more important than producing volume.

“The greatest untapped natural resource isn’t hidden beneath the ground. It’s already being harvested every day.” [Roy Henderson, CEO GCT®]

For more than a century, industrial progress has been measured in volume.  More steel.  More coal.  More wheat, timber, fish, milk, oil and so on…

More production has almost always been seen as the pathway to greater prosperity.

But biology and nature do not work like mining.

Every biological resource already contains extraordinary complexity and value.  Plants, algae, fungi and agricultural crops are sophisticated chemical factories, producing proteins, fibres, pigments, antioxidants, minerals, enzymes and thousands of bioactive compounds through millions of years of evolution.

Yet modern industry often extracts only a fraction of that value.

The remainder is downgraded into low-value applications – or simply discarded.  That is not because the value isn’t there.  It is because our processing systems were largely designed for an era that prioritised volume over optimisation.

Today, however, the pressures facing society have changed.

Growing populations, finite natural resources, climate change and increasing demands on land, water and energy mean that producing ever more biomass is becoming both harder and more expensive.

Perhaps we have reached the point where the most important question is no longer: “How do we produce more?”  Perhaps it is: “How do we recover more from what we already produce?”

That subtle shift changes everything.  Suddenly, agricultural residues become feedstocks.  Food processing by-products become future ingredients.  Marine biomass becomes a platform for multiple industries rather than a single commodity.

Success is no longer measured by tonnes harvested.  It is measured by value recovered.

This is not simply an engineering challenge.  It is an economic one.

Imagine two processors receiving exactly the same tonne of biological material.  One extracts a single product.

The other develops multiple revenue streams from the same biomass.

Both handled the same raw material.  One created a commodity.  The other created an ecosystem.

That difference will increasingly determine which companies and countries succeed in the emerging bioeconomy.

Around the world we are seeing governments invest heavily in growing biomass production.

That investment is important.  But production alone will not unlock prosperity.

The real opportunity lies in recovering more value from every harvest, every crop, every marine resource and every biological feedstock.

In many respects, the next industrial revolution has already begun.  It is no longer about producing more biological material.  It is about understanding its hidden potential.

At Green Cell Technologies®, we believe this is one of the defining industrial opportunities of our time.

Not because of one technology.  But because the world can no longer afford to leave so much value behind.

The future belongs to those who recover more.

If you would like to know how you can recover and/or create more value from what you are already doing, then get in touch…info@greencelltechnologies.com

Unblocking the Seaweed Industry’s Next Bottleneck

As the industry moves from cultivation to commercialisation, are we investing enough in processing infrastructure?

The Seaweed Industry’s Next Bottleneck

As the global seaweed industry gathers in Gothenburg for Seagriculture EU 2026, much of the conversation will rightly focus on scale.

How does it move beyond pilots?

How does it attract investment?

How does it build viable businesses?

How does it create meaningful environmental and economic impact?

These are important questions.

The seaweed sector has spent the last decade proving that cultivation is possible. Farmers, researchers, entrepreneurs and investors have worked hard to move seaweed from a niche activity into a recognised component of the emerging blue bioeconomy.

Today, cultivation techniques continue to improve. New markets are emerging. Governments are taking notice. Investors are becoming increasingly interested in the potential of seaweed as a source of food, feed, biomaterials, biostimulants and bio-based products.

The industry has made remarkable progress.

But as we move from proving that seaweed can be grown to proving that seaweed can be commercialised at scale, a new question emerges.

What happens when the biomass arrives onshore?

Historically, the biggest challenge facing the seaweed industry was cultivation.

Today, that challenge is beginning to shift.

The Next Bottleneck

The next bottleneck may not be growing seaweed.  It may be processing it.

Around the world, significant investment is being directed towards farming capacity, cultivation systems and species development. Yet comparatively little attention is being paid to the infrastructure required to transform harvested biomass into high-value products.  This creates a risk.

As production scales, the industry may find itself capable of producing increasing volumes of seaweed without having sufficient processing capacity to unlock its full value.

In other industries, this challenge is well understood.

Agriculture requires grain silos, mills and processing plants.  Mining requires refineries and smelters, and energy requires transmission and distribution networks.

These sectors recognise that production alone does not create value.  Infrastructure does.

The seaweed industry may be approaching a similar moment.

Beyond Drying and Storage

Processing should not be viewed simply as a post-harvest necessity.  It is a strategic layer within the value chain.  Processing influences:

  • Product quality
  • Nutritional value
  • Bioactive recovery
  • Functional performance
  • Shelf life
  • Manufacturing economics
  • Waste generation.

Most importantly, it determines how much value can ultimately be extracted from each tonne of harvested biomass.

This becomes increasingly important as cultivation costs rise and competition intensifies.

The industry cannot afford to leave value behind.

The Rise of Shared Infrastructure

Perhaps the most important question is not which company will build the next farm.

Perhaps it is: Who will build the processing layer?

Will it be individual producers?

Will it be ingredient manufacturers?

Will it be investors?

Will it be regional clusters?

Will it be public-private partnerships?

The answer may differ by geography, species and market.  However, one thing appears increasingly clear:  Not every grower will be able to justify building a full processing facility.

This creates an opportunity for shared infrastructure models.

Regional processing hubs could provide access to advanced processing technologies without requiring every producer to invest in expensive standalone facilities, until their volumes allow for it.

Such models have the potential to improve efficiency, increase value recovery and accelerate commercial adoption across entire regions.

A Different Type of Investment

As discussions around seaweed finance continue to mature, it may be time to broaden our view of what constitutes an investable asset.  Farms are important. Biomass is important.  But so too is the infrastructure that transforms biomass into market-ready products.

Processing facilities, regional hubs and value-addition infrastructure may ultimately become some of the most important assets in the seaweed economy.  Not because they produce seaweed.  But because they determine what that seaweed becomes.

Looking Beyond the Water

The seaweed industry has spent years proving that cultivation works.  To my mind, the next challenge is proving that value creation can scale alongside it.

That will require investment not only in growing more biomass, but in unlocking more value from every tonne harvested.  

The future of seaweed will not be determined solely by what happens in the water.  It will increasingly be shaped by what happens after harvest.  And that may prove to be the industry’s next bottleneck if we do not take stock now.  


Roy Henderson, CEO of Green Cell Technologies, will be exploring related themes during his presentation at Seagriculture EU 2026 in Gothenburg, Sweden on Wednesday 16 June 2026.

The Bioeconomy Has a Missing Middle – and It’s Processing

A recent FoodNavigator article on functional beverages highlights a challenge that extends far beyond drinks.

The article makes a simple but important point: functional beverages can no longer rely on health claims alone.  Consumers expect products that taste good, deliver credible benefits, feel natural, are priced correctly, and fit into their everyday lives.

That is not just a branding challenge. It is a processing challenge – across the bioeconomy.

The world is investing heavily in promising raw materials. Think seaweed, botanicals, plant proteins, fruits, vegetables, fibres, agri-residues, fly larvae and other biological inputs. Far less attention, however, is paid to the processing layer that determines whether those materials become commercially viable products.

This is the missing middle.

It is the space between what we grow, harvest or collect, and what the market can actually use.

In seaweed, cultivation is advancing, but value is often lost after harvest through outdated, selective or waste-heavy processing methods.

In functional beverages, brands may have access to exciting ingredients, but if processing compromises flavour, texture, stability or bioactivity, the product struggles to deliver.

In plant proteins, performance is shaped not only by the crop, but by how fibres, cells and particulates are treated.

In nutraceuticals and botanicals, the commercial value often depends on how effectively bioactive compounds are released and preserved.

In agri-waste and side-streams, the opportunity is not simply to “use waste”, but to process it intelligently enough to create new value.

In almost every one of these streams, poor or incomplete processing creates waste – either as new by-products, degraded material, spent biomass, or simply unprocessed potential left behind. This means industries are often paying to grow, harvest, transport and handle biological materials, only to discard a significant portion of their value at the processing stage.

The market is not short of biological potential.

It is short of processing systems that can unlock that potential fully, efficiently and consistently.

At Green Cell Technologies, this is where we believe the next major shift will happen.

Our Disruptor® platform, powered by Dynamic Cellular Disruption® (DCD®), is designed to mechanically open cell structures, micronize fibres, fragment fine particulates and sterilise processed material – in a single continuous process with no denaturing. 

That matters because processing is no longer a back-end technical step.

  • It affects yield.
  • It affects taste.
  • It affects texture.
  • It affects bioavailability.
  • It affects waste.
  • It affects cost.
  • It affects whether a product can scale.
  • If the bioeconomy is to deliver on its promise – healthier foods, better ingredients, cleaner industrial inputs, circular value chains and reduced waste – then processing has to move to the centre of the conversation.

The future will not be decided only by what we grow.  It will be decided by how intelligently we process it.

Processing is where biological potential becomes commercial value.

Get in touch with us: info@greencelltechnologies.co.za

Why Do We Eat?

Why Do We Eat? And How We Lost Our Way

We eat for fuel.
At least, that’s what food was always meant to be.

Fuel for the body.
Fuel for the brain.
Fuel for growth, repair, resilience, and health.

And yet, somewhere along the way, we stopped eating to live – and started living to eat.

This shift did not happen by accident.

Over decades, the global food system has been shaped less by what the human body actually needs and more by what markets reward: appearance, texture, mouthfeel, shelf life, and mass appeal. Nutrition – the very reason food exists – has been quietly pushed into the background.

Today, food is judged first by how it looks, how it tastes, and how it feels in the mouth – and only later, if at all, by what it actually does for the body.

This is not a consumer failure.  It is a systemic one.

How we were programmed to eat wrong

Food companies did not set out to make people unhealthy.  But they did set out to make food irresistible, repeatable, and profitable.

Over time, entire systems – including global guidelines and institutional frameworks – reinforced the idea that food is primarily about enjoyment, indulgence, and satisfaction, rather than nourishment and function.

We were conditioned to ask:

  • Does it taste good?
  • Does it look appealing?
  • Does it feel indulgent?

Instead of:

  • Does it nourish?
  • Does it repair?
  • Does it strengthen?
  • Does it sustain long-term health?

The result is a paradox we now live with every day:

  • An abundance of food
  • Rising obesity
  • Growing malnutrition
  • Chronic disease at unprecedented levels

Calories are plentiful. Nutrition is not.

The industry’s reluctance to change outcomes

At Green Cell Technologies, we work at the heart of food processing – the point where raw biological material becomes something humans consume.

Time and again, manufacturers come to us asking for solutions:

  • To improve nutrition
  • To increase bioavailability
  • To reduce waste
  • To create new foods
  • To do better

But just as often, those same manufacturers insist on keeping the same outcomes:

  • The same textures
  • The same mouthfeel
  • The same visual cues
  • The same consumer expectations

Even when those outcomes are clearly no longer working.

This is where the contradiction lies.

You cannot ask for transformation while refusing to change the result. You cannot fix a broken system by recreating it with slightly different inputs.  And yet, the food industry keeps playing the same game – a kind of innovation ping-pong – bouncing between awareness and avoidance, without ever changing direction.

Processing is where real change must happen

What much of the food conversation avoids is an uncomfortable truth:

Nutrition is not unlocked by ingredients alone.  It is unlocked by processing.

You can grow the most nutrient-dense crop on Earth – but if its cellular structure remains intact, much of that nutrition never becomes available to the body.

You can fortify products, add supplements, or label food as “healthy” – but if nutrients are not bioavailable, the body cannot use them.

At GCT, our work is grounded in a simple principle:  Food should work for the body, not just please the senses.

That means rethinking:

  • Texture as a consequence, not a priority
  • Taste as important, but not supreme
  • Appearance as secondary to function

It also means accepting that better nutrition may lead to different outcomes – and that clinging to familiar sensory expectations is part of the problem, not the solution.

The food system does not need more incremental tweaks.  It needs a total reset.

We cannot keep bouncing between:  “We need healthier food” and “But it still has to look, feel, and behave exactly the same.”

That loop is costing us health, time, and credibility.

Manufacturers Must Lead – Not Follow

There is a persistent myth in the food industry that manufacturers are merely responding to consumer demand – that people want indulgence, familiarity, and sensory reward, and that industry has no choice but to comply.

This is convenient.  And it is largely untrue.

For decades, manufacturers have shaped consumer behaviour through formulation, marketing, pricing, and availability.  Taste preferences were not discovered – they were engineered. Expectations around texture, sweetness, saltiness, and indulgence were not inevitable – they were cultivated.

Which means the reverse is also true.

Manufacturers now have a profound opportunity – and responsibility – to lead consumers back toward health.

Instead of pouring billions into marketing food as entertainment, brands can redirect their influence toward education:

  • What food does in the body
  • Why bioavailable nutrition matters
  • How processing affects health outcomes
  • Why nourishment should come before indulgence

Consumers are not incapable of change.  They are simply under-informed.

At GCT, we see this moment as a pivot point. The industry can continue blaming consumer demand – or it can recognise its power to reset the narrative.  Education is no longer a cost.  It is an investment in long-term trust, resilience, and relevance.

Health-forward food systems will not emerge from passive observation.  They will emerge from leadership.

The next generation of trusted brands will be those that choose health over habit.  Manufacturers don’t just feed populations – they shape them.

Returning to first principles

If we are serious about food security, public health, and sustainability, we must return to first principles and ask again:

Why do we eat?

Until the answer becomes “to nourish and sustain life” – not “to satisfy engineered cravings” -we will continue to build food systems that fail the very people they are meant to serve.

At Green Cell Technologies, we believe the future of food lies not in more distraction, but in better processing, deeper nutrition, and the courage to change outcomes.

If you’re a manufacturer serious about changing outcomes – not just ingredients – we’d welcome the conversation. info@greencelltechnologies.com

Processing Will Define Sustainability & Industry in 2026

From Waste to Value: How Intelligent Processing Will Shape Our Future

As another year draws to a close, the global conversation around sustainability, circularity and food security grows louder.  There are more panels, more pledges, more reports, and more “bold visions” than ever before.

And yet, a quiet truth is emerging beneath the noise: Despite all the talk, the world is still wasting extraordinary amounts of valuable biological material – simply because it does not process it intelligently.

At Green Cell Technologies (GCT), this is not a new realisation.  It is the reason we exist.

For more than 20 years, we have been saying the same thing – often to empty rooms:

“Sustainability will not be won or lost in what we grow.  It will be decided by how we process what we already have.”

As we look ahead to 2026, it is becoming clear that the world is finally catching up to that idea. The coming year will mark a turning point – not because new resources have been discovered, but because industries are being forced to confront the consequences of ignoring the “middle” of the value chain for far too long.

Below are the defining shifts we see shaping 2026 – and why processing sits at the centre of all of them:

1. From Net-Zero Promises to Material Accountability

The era of sustainability as aspiration is ending.

By 2026, companies will increasingly be judged not by their commitments, but by what physically happens to materials moving through their systems.  Regulators, investors and procurement teams are asking harder questions:

  • Where does waste go?
  • How much value is lost?
  • What resources are still being landfilled, incinerated, or downcycled?

At GCT, we have long argued that sustainability claims mean little if waste still exists.  Offsets do not replace lost nutrients.  Pledges do not recover discarded protein.  Reports do not rebuild degraded ecosystems.

Material accountability begins with processing – or it does not begin at all.

2. Processing Sovereignty Becomes Strategic

Global supply shocks, geopolitical instability and climate volatility have exposed the fragility of long, centralised supply chains.  As a result, nations and industries are reassessing where and how value is created.

In 2026, we will see a strong move toward processing sovereignty – the ability to convert local biomass, residues and by-products into usable products at or near source.

This is not about isolationism.  It is about resilience.

For two decades, GCT has designed technologies that enable distributed, scalable processing, precisely because we understood that shipping raw materials across continents – only to import finished goods back again – was neither sustainable nor sensible.

That insight is now becoming policy.

3. “Waste” Is Being Reclassified – and Time Is Running Out

Across sectors, what was once dismissed as waste is being redefined as a strategic resource. Brewers’ spent grain (BSG), crop residues, food processing offcuts, feathers, shells, skins and pulp are no longer seen as inevitable losses – but as under-utilised assets.

This reclassification is accelerating due to regulation, cost pressures, and shifting consumer expectations. But there is a critical caveat:

Recognising value is not the same as unlocking it.

Time and again, we see industries acknowledge the potential of by-products – only to overlook the processing technologies required to make them usable at scale, and ones that retain the essential goodness in the source product.  

At GCT, we identified this risk years ago.  That is why we built Disruptor® and Dynamic Cellular Disruption® (DCD®): to ensure that “waste” could be converted into value before regulatory and ecological windows closed.

As we approach 2026, that window is narrowing fast.

4. The Next Protein Revolution Won’t Come from Planting More

The global protein conversation is shifting.  While novel crops and alternative farming systems remain important, the fastest, most efficient gains will come from recovering protein from what is already produced.

Agro-residues, brewing by-products, and processing streams contain vast amounts of locked-in nutrition – protein that never reaches people, animals or soil simply because it remains trapped inside intact cell walls.

For more than 20 years, GCT has maintained that the next protein revolution would be a processing revolution – not an agricultural one.

By 2026, that position will be difficult to dispute

5. The End of “Pilot Purgatory”

Across sustainability and food systems, fatigue is setting in.  Endless pilots, demonstrations and proof-of-concepts have delivered insight – but little transformation.

As timelines compress and pressure intensifies, industries are increasingly demanding technologies that are deployable, proven and scalable now.

This shift plays directly to GCT’s strengths.  We did not build Disruptor®- tech as a future concept.  We built it because we believed the world would eventually need solutions that could move from idea to infrastructure without delay.

That moment has arrived.

6. Processing Becomes the New Battleground of Power

As biological resources gain strategic importance, attention is turning to who controls processing – and how it is done.  Intellectual property, energy efficiency, yield optimisation and waste elimination are becoming decisive competitive factors.

Extraction-heavy, solvent-based and energy-intensive approaches are increasingly under scrutiny.  The future belongs to technologies that can deliver full-value recovery without environmental compromise.

This is not a trend we are reacting to.  It is the landscape we anticipated when we chose whole-material processing over partial extraction decades ago.

7. Circularity Moves from Design to Infrastructure

For years, circular economy discussions focused on product design.   But as 2026 approaches, the limitation is clear:

Circularity fails without processing infrastructure.

No amount of clever design can compensate for the absence of systems capable of converting biological material into safe, valuable outputs at scale.

At GCT, we see processing as the invisible infrastructure layer of the circular economy – the part that determines whether circularity remains a concept or becomes reality.

8. Nutrition, Not Calories, Defines Food Security

Food security debates are evolving beyond volume. The real challenge is now nutrient access and bioavailability – ensuring that what is consumed can actually nourish humans, animals and ecosystems.

Processing at the cellular level is essential to this shift.  Unlocking nutrients requires more than grinding or drying. It requires technologies capable of releasing what biology has tightly bound.

This has been central to GCT’s thinking from the start.

9. Time is the New Scarcity

Perhaps the most defining reality heading into 2026 is this:

Time has become the scarcest resource of all.

Climate thresholds, regulatory deadlines and ecosystem tipping points leave little room for delay.  The world does not lack ideas.  It lacks the willingness to deploy what already works.

For over 20 years, GCT has been preparing for this moment – not because we wanted to be early, but because we understood that waiting would eventually become a luxury the planet could not afford.

Looking Ahead

The trends shaping 2026 are not abstract.  They are converging on a single, unavoidable truth:

The future of sustainability, food security and circularity will be defined by processing.

At Green Cell Technologies, this is not a prediction.  It is a continuation of the work we began two decades ago – long before it was fashionable, funded, or widely understood.

The world is finally asking the right questions.

The challenge now is whether it is ready to act on the answers.

If you want answers, then email info@greencelltechnologies.com

Turning Agro-Residue into High-Value Ingredients

The New Frontier of Waste Utilisation

Why the world’s most overlooked resource may also be its most profitable

From waste to wealth: the hidden opportunity in agro-residues

Every harvest produces two things: a primary crop, and everything else.
For decades, that everything else – husks, stems, pulp, peels, and by-products – has been treated as waste.  Globally, we generate billions of tonnes of agricultural residue each year. Some is composted or burned; most is left to rot.

According to the latest analyses from IEA Bioenergy and MDPI, this biomass represents one of the world’s most vast, renewable, and under-utilised feedstocks.  Yet it’s also the raw material for a new industrial revolution – one where sustainability, profitability, and advanced processing meet.

The world is finally catching up – but the clock is ticking

At Green Cell Technologies®, we’ve been talking about this opportunity for years:

  • that waste is not waste,
  • that residues are resources, and
  • that value lies hidden inside every cell of biologically rich material.

Only now, is the global market truly waking up to the idea of redefining ‘waste’.  But as more organisations talk openly about valorisation and upcycling, one blind spot keeps repeating itself: processing is still being overlooked.

Companies recognise the need for better resource use. They know their by-products have value.  They see technologies like Disruptor® and DCD® as viable, immediate solutions.

And yet, the time between considering doing something and needing to do something has shortened dramatically.  The window in which we can correct our global waste problem is shrinking – not because of lack of will, but because we have not transformed how we process what we already have.

This is why action now matters more than ever.

The scale of the untapped resource

The FAO estimates that roughly one-third of all food produced globally – about 1.3 billion tonnes per year – is wasted. A significant share of that loss happens at processing and post-harvest stages.

Every ton of agricultural product generates 0.2–0.5 tonnes of residue – material bursting with nutritional, structural, or biochemical potential.

A few examples show just how valuable these residues are:

  • Tomato skins and seeds – high in lycopene, antioxidants.
  • Citrus peels – rich in pectin, flavonoids, and essential oils.
  • Wheat bran, corn fibre, rice husks – full of protein, minerals, and functional fibre.
  • Coffee pulp and fruit pomace – densely packed with polyphenols.

These are not waste streams. They are ingredient streams, waiting for better processing.

The problem: old processing for a new world

Legacy food and agricultural systems were designed for extraction – not optimisation.
They captured one commercially valuable component and discarded the rest.

Today, that model collapses under modern expectations for sustainability, efficiency, carbon reduction, and resource responsibility.

Key barriers remain:

  • Energy-intensive, toxic and waste producing drying, milling, and solvent extraction
  • Severe nutrient & compound degradation
  • Inconsistent output due to variable feedstocks
  • Lack of scalable continuous-flow solutions
  • Perception and regulatory challenges around “waste-derived” inputs

Without technologically advanced processing, industries cannot unlock the true value of agro-residue – or meet their sustainability targets.

Unlocking every usable molecule

GCT’s Disruptor® and Dynamic Cellular Disruption® (DCD®) technology overturn the limitations of conventional processing.
These systems deliver:

✅ Zero-waste output – nothing is lost
✅ No solvents or harsh chemicals required
✅ Superior nutrient and bioactive preservation
✅ Continuous scalability
✅ High-spec ingredient outputs suitable for food, feed, nutraceutical, and biomaterial applications.

Our technology was built for one purpose:
to release the maximum possible value from any biological material – sustainably, consistently, and at industrial scale.

Case Studies: When ‘Residue’ Becomes Revenue

Citrus Peel → Functional Fibre & Antioxidants
Citrus processors generate mountains of peel.  With DCD®, those peels become functional dietary fibres and flavonoid-rich extracts for beverages and supplements.

Tomato Skins → Lycopene Concentrates
What once went to landfill can now be refined into nutrient-dense colourants and antioxidant extracts – all solvent-free.

Coffee Pulp → High-Value Bioactive Streams
Instead of causing environmental damage, pulp becomes a source of polyphenols and agricultural soil enhancers.

Each example illustrates how processing defines the destiny of residue.

The economics: transforming cost centres into profit engines

Traditional waste disposal is a rising cost burden. Landfill fees, transport, and regulatory compliance are squeezing margins.

With GCT’s processing approach, manufacturers can:

  • Create multiple ingredient lines from a single waste stream
  • Reduce operating costs and waste-handling overheads
  • Improve carbon metrics & ESG rating
  • Unlock new markets for upcycled and natural ingredients
  • Achieve faster ROI through diversification

Waste becomes income.
Residue becomes asset.
Processing becomes competitive advantage.

A market actively seeking upcycled inputs

Major brands – from global FMCGs to niche food innovators – are demanding upcycled, traceable, high-value ingredients as part of their sustainability commitments.

This is not a passing trend. It’s a procurement revolution.

Manufacturers who can supply consistent, specification-grade outputs from residues will be the suppliers of choice in the next decade.

The next frontier starts with processing

The world is finally recognising that agro-residue has value – but recognition without action is not enough.

We can no longer afford delays in adopting the processing technologies that already exist.

GCT has been ready for years.
The world is catching up – but time is catching up too.

Let’s move from wasteful thinking to value-driven utilisation, before the planet pays the price for our hesitation.

Contact Green Cell Technologies to unlock the full value in your residue streams. info@greencelltechnologies.com

The Biomaterial Boom – and the Blind Spot

From Cultivation to Consumer

Why processing must be the next leap in the biomaterials economy – how next-generation processing technologies will determine who wins in the bio-based future.

Around the world, industries are racing to replace petrochemical feedstocks with renewable, biological ones. From kelp-based packaging to mushroom leather, from hemp fibres to food waste-derived biopolymers, the biomaterials revolution is well underway.

But there’s a critical piece missing in this story – and it’s hiding in plain sight: processing.

We’re talking about what happens after cultivation, harvesting or fermentation – the transformation of raw bio-matter into usable, scalable, market-ready products.  It’s where 80% of the environmental footprint and 100% of the commercial viability are determined.  Yet, despite the headlines around cultivation breakthroughs, processing remains the least-funded, least-optimised and least discussed link in the biomaterial value chain.

From Growth to Market: The Forgotten Middle

The value chain for any bio-based product can be summarised as:

Cultivation – Processing – Specification – Market.

  1. Cultivation – growing or harvesting biological material (seaweed, mycelium, algae, crops, etc).
  2. Processing – breaking down, refining or reforming that material into a functional form.
  3. Specification – meeting target physical, chemical or nutritional parameters.
  4. Market – delivering consistent, certifiable material to buyers.

Most of today’s investment and innovation sit at the first and last steps – cultivation and market. What’s often overlooked is that processing determines whether a promising material ever reaches specification.

Without intelligent, efficient, and circular processing, even the most sustainable raw materials risk becoming the next wave of industrial inefficiency – energy-hungry, waste-producing, and economically marginal.

The Bioeconomy’s Bottleneck

Governments and the private sector alike are championing the “bioeconomy” – an ecosystem built around converting biomass into multiple high-value products across food, feed, energy, and materials.

According to OECD and EU frameworks, the bioeconomy could represent over $8 trillion globally by 2030, but the gap between lab innovation and industrial scalability remains vast.

The main bottlenecks include:

  • Variability of feedstocks – no two biomass streams are chemically identical.
  • High processing costs – drying, milling, or solvent extraction are energy-intensive, often toxic and always wasteful using antiquated technology.
  • Loss of functionality – many existing methods damage nutrients, polymers, or fibres.
  • Lack of standardisation – manufacturers can’t guarantee consistent specifications at scale.
  • Regulatory friction – difficulty in certifying “green” processes without reliable data.

These challenges aren’t about biology – they’re about engineering.  The world needs scalable, continuous, and zero-waste processing innovation that can match the pace of cultivation breakthroughs.

At Green Cell Technologies (GCT), we’ve been building that missing link.
Our patented Disruptor® and Dynamic Cellular Disruption® (DCD®) systems deliver a mechanical, solvent-free method of unlocking the full potential of biological materials – from plant fibres and seaweed to food residues and bio-waste.

What sets GCT apart is our process-first philosophy:

✅ Zero-waste output – every usable molecule and fibre recovered.
✅ No solvents, little to no degradation – maximum preservation of nutrients and structural integrity.
✅ Continuous scalability – adaptable from pilot to industrial throughput.
✅ Cross-sector versatility – applicable to food, nutraceuticals, biomaterials, cosmetics, and more.

Whether you’re working with kelp, hemp, or crop residues, Disruptor® technology enables you to transform low-value biomass into high-spec ingredients ready for market.

Closing the Loop: Cultivation Meets Commercialisation

Consider the difference between growing seaweed and using it:

  • Cultivation gives us a renewable resource.
  • But processing – efficient, zero-waste, nutrient-preserving processing – is what turns it into food ingredients, bioplastics, textiles, or pharmaceuticals.

That’s the conversion from promise to product, from pilot to profit.
GCT’s technologies are the bridge that allows companies to make that leap – not ten years from now, but today.

Why This Matters for Manufacturers and Investors

For manufacturers:

  • Future-proof your production against regulatory tightening and carbon taxes.
  • Unlock new revenue streams from by-products previously treated as waste.
  • Reduce energy inputs and improve lifecycle assessments (LCAs) instantly.

For investors and corporate innovation teams:

  • Lower risk – proven hardware and IP portfolio in market.
  • Cross-industry play – relevance across food, feed, packaging, bio-pharma, and cosmetics.
  • Immediate ESG value – tangible decarbonisation through process redesign.

The Next Leap Starts with Processing

The biomaterials revolution isn’t just about what we grow – it’s about what we do with it.
If cultivation was the first leap, processing is the next.

At Green Cell Technologies, we’re ready to help industries move from extraction to transformation – from raw potential to real-world performance.

Get in touch to explore how GCT’s Disruptor® and DCD® systems can help you process smarter, waste less, and lead the bio-based future. Drop us a line on info@greencelltechnologies.com